4. Income, is the hero for retirement
We’ve planned the menu, now it’s time to deliver the flavour. Maximising retirement income is the ultimate goal and should be the hero of the dish that is served up. While members’ best financial interests usually focuses on fund expenses, the real measure of success is the income members enjoy in retirement.
There are constraints to manage. A fund’s income solution must provide more value than it costs, but it doesn’t have to be individually tailored for every member. Some high balance members might benefit from the additional tailoring, but the role of a superannuation fund trustee is to meet the collective needs. Funds can support members by providing access to quality financial advice without draining the collective resources of other members. This can help members to find a suitable, high-quality retirement income solution.
5. Blending the herbs & spices
The right mix of herbs and spices can take the dish to the next level. To deliver a high-quality retirement income solution, this means a blend of:
- Growth investments to support income in later years by growing capital, with some volatility;
- Stable assets, that will maintain capital with some income and flexibility; and
- Lifetime income streams that ultimately convert the committed capital to income that lasts throughout retirement.
While some retirees will have specific dietary requirements, funds should have each of the core ingredients available to meet members’ varying needs.
6. Trust the Chef
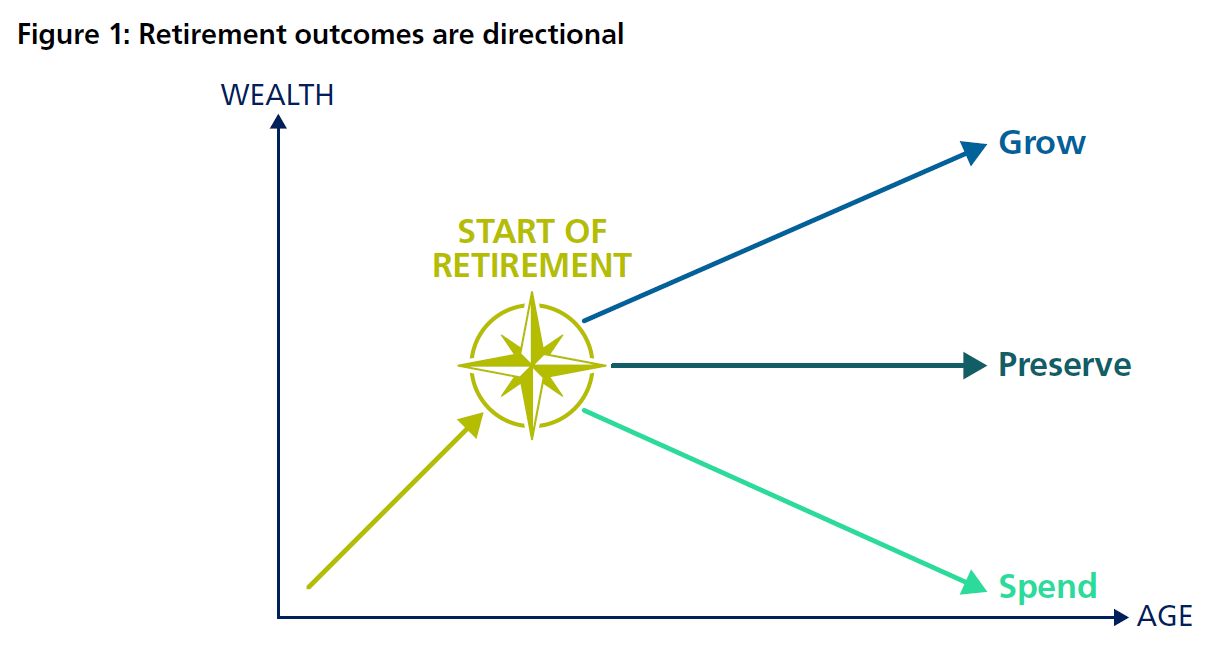
While wealth accumulation looks the same for most Australians, a more customised approach is needed for the retirement phase of superannuation.
Without guidance, retirees might struggle to combine the right financial ingredients, risking an outcome that doesn’t meet their needs. The Chef’s Menu pairing guides retirees to the right flavour combinations.
For example, a simple menu might suggest: 50% in growth investments; 25% in stable liquid investments; and 25% in a lifetime income stream. Retirees can then adjust this base to suit their personal tastes, ensuring the plan reflects their unique preferences and goals.
While some retirees are confident experimenting, others may prefer to “trust the chef”, relying on their fund or seeking out a financial adviser to design a bespoke solution. Ideally, funds would help members access this advice, in addition to providing good base options.
7. Consider BYO
The right wine can bring a meal together. BYO allows members to pair the menu with a vintage that suits them best. Funds must account for members who bring their own financial accompaniments to the table.
For example, where a member’s partner has a reversionary defined benefit pension, adding another lifetime income stream might be unnecessary. Alternatively, someone might have a string of investment properties or other assets outside of super. A fund might not be aware of these components, but retirement income solutions need flexibility to ensure there is no double-up.