Insights
Macro Musing: Will Artificial Intelligence revolutionise the economy and financial markets?
Dr Jonathan Kearns - Chief Economist
31 March 2025
How have older members’ retirement income preferences changed following the sustained high inflation environment?
This note addresses key questions for investors and finance professionals: How much will AI boost to firms’ output and profits? Or has the hype already exceeded its near-term potential? How will AI influence different assets’ absolute and relative returns? And closer to home, will AI upend financial sector work?
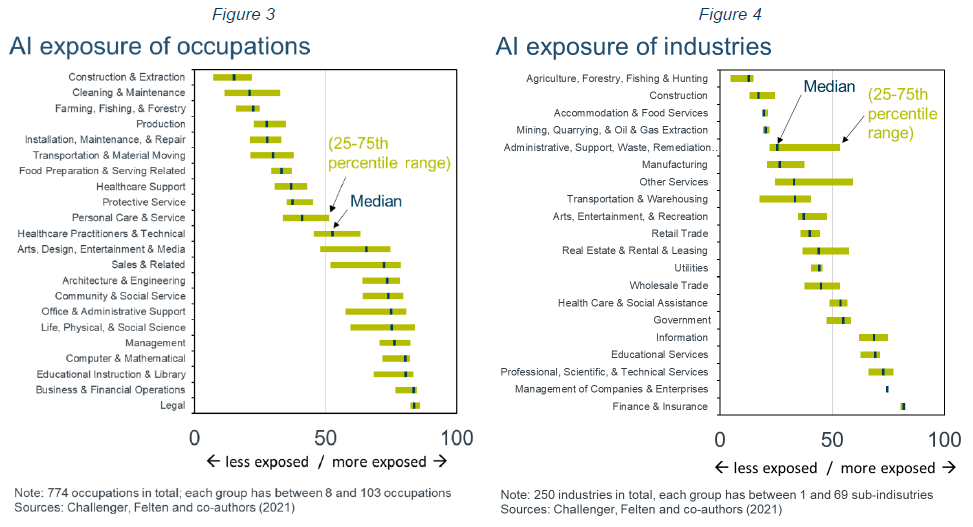
These indices highlight that knowledge-based jobs are most exposed to AI. Of the 774 jobs that the authors analyse, the three most exposed to AI are financial examiners, actuaries and genetic counsellors. At the bottom of the list of professions impacted by AI, not surprisingly, comes dancers, fitness trainers and aerobics instructors.
When the 774 jobs are aggregated to the 22 job categories shown in Figure 3, it is Legal that is most exposed, closely followed by Business & Financial Operations. Given the greater impact of AI on knowledge-based jobs, the industries with a larger share of those jobs are most exposed to AI. Of the 250 industries the authors consider, seven of the top 10 are finance-related. When those 250 industries are aggregated to the 20 groups shown in Figure 4, it is the Finance & Insurance industry group that shows as most exposed to AI.
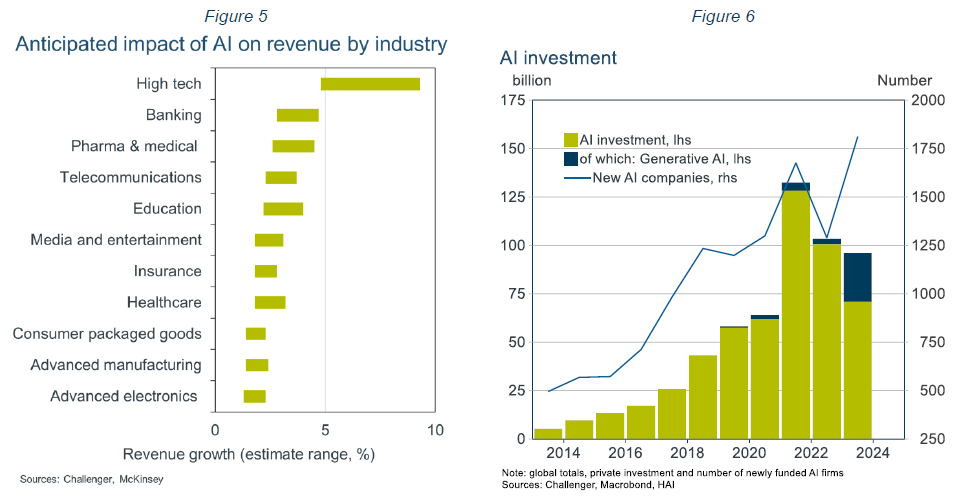
McKinsey have also estimated the impact that AI will have on the revenue of various sectors. In their study, banking ranks second only to high tech in the expected boost to revenue from AI (Figure 5).
There are other reasons why AI will significantly affect the financial sector beyond the skills of finance workers:
The financial sector is heavily regulated with substantial risk, compliance and legal responsibilities. AI could assist financial institutions to satisfy these regulations. It could also assist with fraud detection and risk management. But equally, there is a significant risk that automation and AI could result in inadvertently breaching regulations or realise financial or operational risks. Regulators will no doubt then be cautious on how financial institutions use AI, which could slow its uptake.
There is substantial investment in AI (Figure 6) and so even if only a portion of the claimed benefits materialise, structural change will produce winners and possibly losers. It is important to note that the sectors with the greatest exposure to AI will not necessarily have the largest increase in output. There are many different channels through which AI will impact the economy, as discussed by Acemoglu and Restrepo (2018) and Acemoglu (2024a). Industries that have an AI-induced productivity boom should experience a decline in their relative price and so see some increase in demand. In contrast, industries that get little boost to productivity from AI will have an increase in their relative price, and so if everything else is unchanged would experience a relative decline in output. This is the ‘substitution effect’.
There is also an ‘income effect’ because higher productivity increases aggregate output and demand across all sectors. However, this increase in demand will not be equal across all sectors. When we become richer, we don’t spend the additional income equally across all types of goods and services. For example, doubling our income will not induce us to spend twice as much on food. But we might spend more than twice as much on travel.
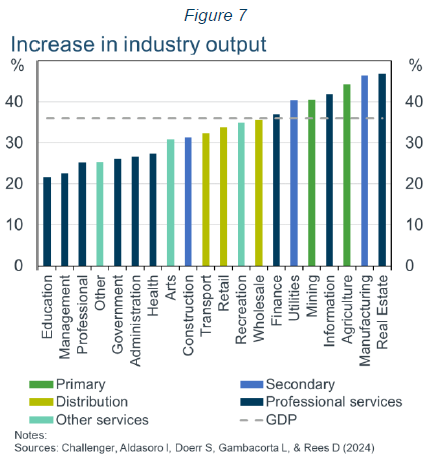
Authors at the Bank for International Settlements used a model of the whole economy, and the AI impact on industries as shown above, to assess each industry’s increase in output (see Aldasoro and co-authors (2024). Notably, while AI has a large impact on many service industries, the study projects that most service industries will have a smaller increase in output than the economy-wide increase (35% in their simulation). Rather, the biggest increases in output come, perhaps surprisingly, in primary industries (agriculture and mining) and a mix of some professional services and secondary industries, such as Manufacturing (Figure 7). Notably, even though finance is highly exposed to AI, finance sector output is projected to only increase in line with aggregate output.
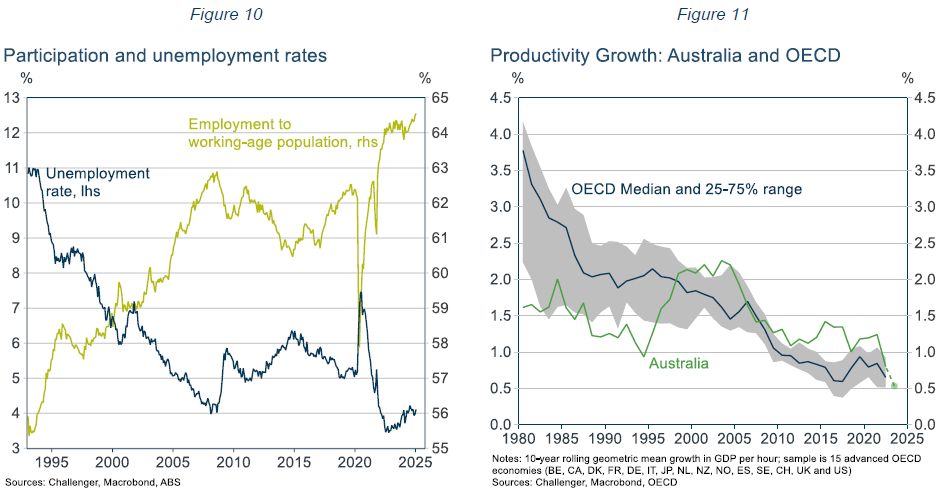
With this remarkable surge in the capabilities and uptake of technology you might expect to see a reduction in the demand for workers, a perennial concern since the Luddites in the industrial revolution. Yet, the computer age in Australia has seen the unemployment rate decline and the share of the working-age population that is working reach record highs (Figure 10).
With productive computers and technology ubiquitous in our work lives you again would expect they have boosted productivity growth, improving living standards. As Nobel Laureate Paul Krugman (1997) noted, “productivity isn’t everything, but in the long run it is almost everything.”
But as another economics Nobel Laureate, Bob Solow famously wrote in 1987 “You can see the computer age everywhere but in the productivity statistics.” Today, his comment seems remarkably prescient. With annual productivity growth rates across OECD economies having declined from around 2% to ¾% over the computer age, it’s hard to see a benefit from computers and technology in the productivity statistics, a point also emphasised by Gordon (2014) (Figure 11). No doubt computers have boosted productivity, but not by nearly enough to offset factors that have pushed productivity lower including outsourcing manufacturing to Asia and the relative growth of service jobs.
Recent developments in AI have significantly increased its versatility, enhancing its capabilities across a range of work tasks. Large language models (LLMs), such as ChatGPT and DeepSeek, that underlie generative AI can be applied to many purposes, unlike earlier AI systems designed for a specific task or purpose. Innovations in multimodal capabilities (text, audio, video) have further broadened the scope of tasks where AI can match or even exceed human performance. As with many new technologies, no doubt there will be productive uses beyond what we can currently imagine.
AI’s recent achievements show just how fast it is evolving(see for example Furman and Seamans, 2019).
The ability to deploy AI within closed corporate IT systems is enabling businesses to adopt AI and develop AI without sharing confidential material, accelerating both take-up and innovation.
Various studies have measured how AI can boost productivity for a specific job. Brynjolfsson and co-authors (2023) analysed 5,000 customer support agents who were given an AI assistant trained using audio and performance metrics from agents’ interactions with customers.3
The AI assistant was able to increase agents’ productivity by 14% on average relative to a control group who did not get the AI assistant. Newer, less skilled, workers had a 34% improvement. Seemingly the AI assistant enabled all agents to perform as if they had the skills of the best performing agents used to train the AI assistant.
Similarly, Dell’Acqua and co-authors (2024), examining consultants’ ability to perform a simulated task, found a 17% increase for the top-half of skilled participants and a larger 43% increase in productivity for low skilled participants.
However, studies examining productivity gains have focused on jobs or tasks where output for which productivity can be directly measured and, presumably, for which AI is expected to improve productivity. We cannot extrapolate these results to all jobs or the whole economy.
Barely a day goes by without a politician or business leader calling for productivity growth as the cure for some economic ailment. There has been no growth in productivity in Australia since before the pandemic, and nobody likes stagnating living standards.
An increase in productivity reduces the labour a firm needs for a given output, reducing the cost of production. That results in some combination of lower prices and higher returns to capital and labour. But increased efficiency does not mean reduced overall demand for labour. Higher aggregate income means more spending, adding to demand for labour in the economy. And productivity’s cost savings mean the economy can grow faster without stoking inflation. If the increase in productivity is uneven across the economy, there are also distributional effects as some sectors grow faster than others and some workers need to retrain for new jobs.
Widespread adoption of AI will increase productivity and output and drive investment to support AI, but how big will this effect be? To assess the economy-wide impact of AI requires a broader approach than the studies above.
The impact of AI will vary across different types of jobs and so across different industries and sectors. It will be greatest on knowledge-based jobs and smallest on more physical jobs. Notably, this contrasts with historical technological advancements (such as mechanisation and IT) which have replaced manual jobs and simpler office jobs such as data processing. In one extensive study, Felton and co-authors (2021) considered 774 occupations across 250 industries and assessed how well 52 cognitive and physical abilities required in each of those occupations can be performed by 10 specific AI applications (such as image recognition, language modelling, and speech recognition). Estimates such as these can be aggregated to produce an economy-wide assessment of the increase in aggregate productivity and GDP growth from AI.
There is a wide range of estimates of the impact of AI, which depend on the underlying assumptions:
Some part of the difference between high and low estimates depends on timing. Acemoglu believes that AI has the potential to lead to fundamental changes in research, innovation and work practices. But he believes that generative AI is not yet capable of fundamental productivity-boosting changes. Rather, over the next 10 years AI will only produce incremental improvements in existing production, hence the lower estimate. Other researchers are also sceptical AI’s short-term impact on productivity. As Manyika and Spence (2023) and others note, there are substantial short-term hurdles including the maturity of the technology, the speed of take-up, availability of workers with AI skills, availability of chips and other required hardware, regulatory barriers and internal operational processes.
Given the use of AI in businesses is new, history is not guide to the implications for productivity and growth. This highlights the huge uncertainty about the impact of AI on productivity and the economy.
AI will reshape the economy as some sectors benefit more from AI, leading to shifts in relative prices, and importantly rising incomes and consumption. Indices that demonstrate the relative exposure to AI of different occupations (Figure 3) and industries (Figure 4) can be produced from the work of Felton and co-authors (2021).
AI has great promise for central banks’ – ranking 15th out of 250 industries in terms of the impact of AI on their work – but their job of managing the economy will be made harder by the uncertain impact of AI on the economy.
Higher productivity will increase the potential growth of the economy, and so how fast the central bank can allow the economy to grow without stoking inflation. But uncertainty about how the adoption and use of AI will affect workers’ efficiency will add to uncertainty about productivity growth. We saw in the 1970s how high inflation and unemployment can result when central banks misinterpret potential output growth and the extent of spare capacity in the economy (‘output gaps’).
Interpreting the productivity, underlying inflation and full employment trends will also be complicated by the shifts in relative prices and employment across sectors. Substantial labour reallocation could increase the equilibrium unemployment rate as labour slowly retrains for different roles. The economic dynamics will also depend on how quickly different sectors adopt AI and how quickly households adjust their spending patterns in response to higher income.
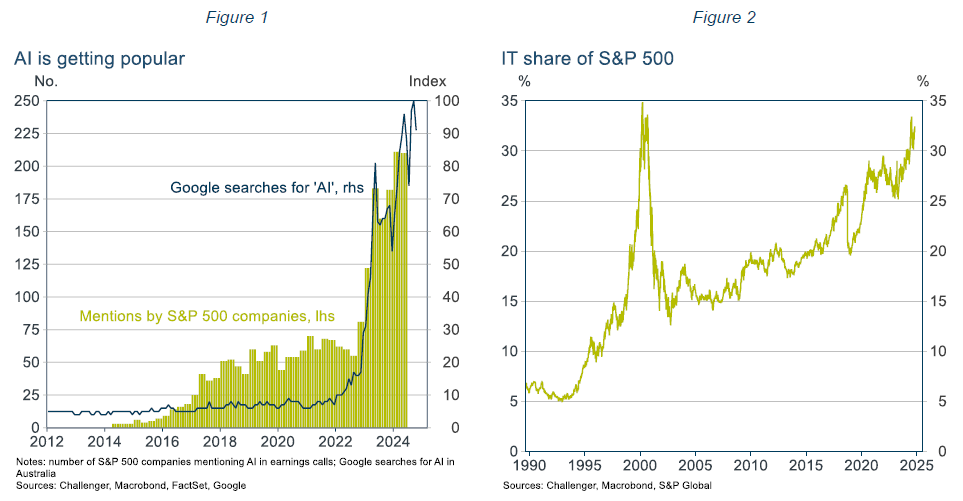
As with any significant structural change AI brings opportunities and risks for investors. The extent of these changes will depend on the speed and breadth of the take-up and its efficacy.
AI has great promise, but there are also many risks to consider.
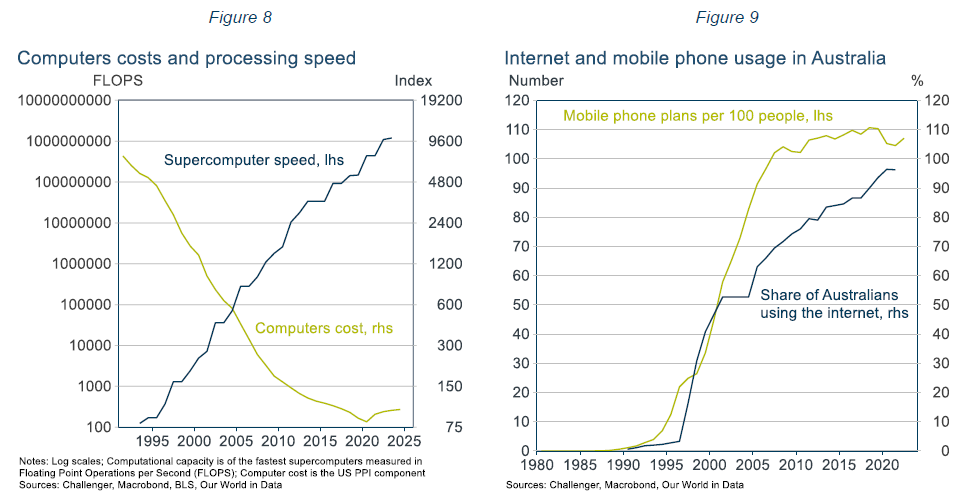
Outcomes in the computer age provide a cautionary perspective for AI exuberance. Advancements in computing over the past 30 or 40 years have been nothing short of phenomenal. The cost of computers has fallen by 99% since early 1990, measured on a quality adjusted basis (Figure 8). And the performance of today’s supercomputers, measured in FLOPS (Floating Point Operations per Second), is approximately 10 million times what it was in the early 1990s. It has been reported that an iPhone is more than 5,000 times faster than a supercomputer from the early 1980s, and 900 million times faster than the guidance computer that took Apollo 11 to the moon.
Technology is now deeply embedded in both our work and personal lives. Since the first mobile phones appeared in the late 1980s, the number of mobile phone plans in Australia have surpassed the total population (Figure 9). Likewise, internet access is universal today but was effectively non-existent in 1990.
AI has immense potential, but like any structural shift, it will create winners and losers. Ensuring large numbers of society are not left behind will help reduce resistance to AI and will promote more equitable outcomes. Diverse outcomes across industries and firms also create huge opportunities, and risks, for investors.
One certainty is that AI will enable financial analysts and economists to produce a larger volume of work – swamping our inboxes. Fortunately, AI will be there to help, by summarising the flood of information. There’s a wonderful irony to the prospect of AI intermediating the work of AI. The key question is, does that leave us better informed?
References
Acemoglu, D., (2024a) The Simple Macroeconomics of AI (No. w32487). National Bureau of Economic Research.
Acemoglu, D., (2024b) Are we ready for AI creative destruction? Project Syndicate
Acemoglu, D., & Johnson, S., (2023) What’s wrong with ChatGPT? Project Syndicate
Acemoglu, D., & Restrepo, P. (2018). Artificial intelligence, automation, and work. In The economics of artificial intelligence: An agenda (pp. 197-236). University of Chicago Press. NBER working paper version.
Aldasoro, I., Doerr, S., Gambacorta, L., & Rees, D. (2024). The impact of artificial intelligence on output and inflation (No. 1179). Bank for International Settlements.
Brynjolfsson, E., Li, D., & Raymond, L. R. (2023). Generative AI at work (No. w31161). National Bureau of Economic Research.
Cazzaniga, M., Jaumotte, M. F., Li, L., Melina, M. G., Panton, A. J., Pizzinelli, C., ... & Tavares, M. M. (2024). Gen-AI: Artificial intelligence and the future of work. International Monetary Fund.
Chui, M., Hazan, E., Roberts, R., Singla, A., & Smaje, K. (2023). The economic potential of generative AI. McKinsey and Co report.
Dell'Acqua, F., McFowland III, E., Mollick, E. R., Lifshitz-Assaf, H., Kellogg, K., Rajendran, S., ... & Lakhani, K. R. (2023). Navigating the jagged technological frontier: Field experimental evidence of the effects of AI on knowledge worker productivity and quality. Harvard Business School Technology & Operations Mgt. Unit Working Paper, (24-013).
Felten, E., Raj, M., & Seamans, R. (2021). Occupational, industry, and geographic exposure to artificial intelligence: A novel dataset and its potential uses. Strategic Management Journal, 42(12), 2195-2217.
Furman, J., & Seamans, R. (2019). AI and the Economy. Innovation policy and the economy, 19(1), 161-191.
Goldman Sachs (2024). Gen AI: Too much spend, too little benefit. Goldman Sachs Global Macro Research, (129), 25. Gordon, R. J. (2014). The demise of US economic growth: restatement, rebuttal, and reflections (No. w19895). National Bureau of Economic Research.
Haque, A., Milstein, A., & Fei-Fei, L. (2020). Illuminating the dark spaces of healthcare with ambient intelligence. Nature, 585(7824), 193-202.
Krugman, P. R. (1997). The age of diminished expectations: US economic policy in the 1990s. MIT press.
Manyika, J., & Spence, M. (2023). The Coming AI Economic Revolution: Can Artificial Intelligence Reverse the Productivity Slowdown?. Foreign Aff., 102, 70.