Loading component...
Loading component...
Loading component...

Download the full article below.
Gifts more than the social security gifting limits ($10,000 per financial year and up to $30,000 over 5 financial years) are assessed as deprived assets for social security and aged care means testing. Deprived assets are assessed under the assets test and are subject to deeming rules under the income test for a period of 5 anniversary years from the date of gift. After this period, the deprived asset is no longer assessed.
As the Challenger Aged Care Calculator is not a full financial planning modelling software, it has certain limitations and one of these limitations is the ability to model deprived assets. From time to time the Challenger Tech Team will enhance the tool based on demand and feedback received from our users. Given recent demand and feedback, we will look to add functionality to capture deprived assets in the calculator.
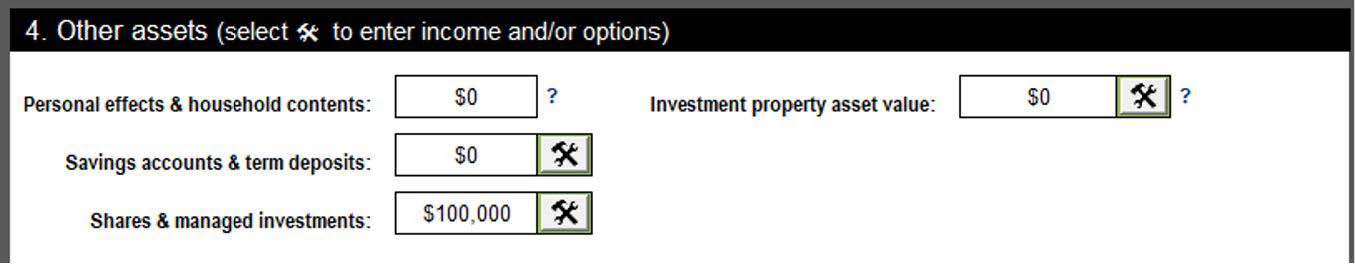
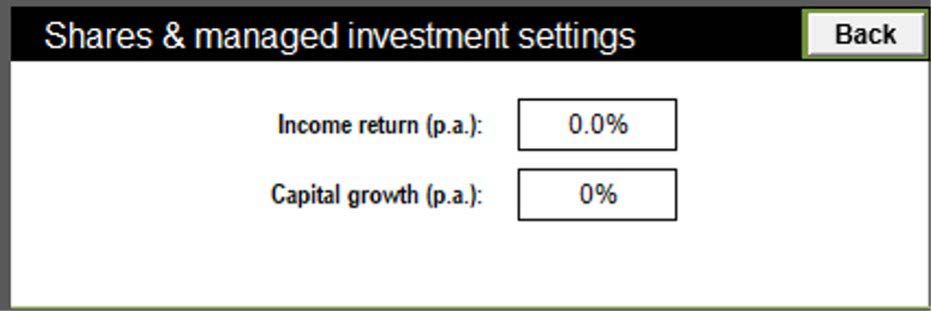
In the interim, users can capture deprived assets by including them into the “Shares & managed investments” field and adjusting down the growth and income assumptions to take into account that deprived assets don’t ‘grow’ or provide income. As a simple example, if a client has $100,000 in deprived assets and does not have other shares or managed investments, the deprived asset can be captured by entering $100,000 into the ‘Shares & managed investments’ field and zeroing out the income and growth settings.
Note however that as the tool currently does not automatically reduce assets after the deprivation period ends, any projections in the ‘analyser’ tab will only be accurate for the number of years until the deprived asset is no longer assessable. This can be up to 5 anniversary years depending on when the client made those gifts.
Additionally, estate values shown in the analyser tab would also be overstated by the deprived asset.