Loading component...
Loading component...
Loading component...
To stay up to date on the latest economic insights, subscribe to Macro Musing on LinkedIn.
Various studies have measured how AI can boost productivity for a specific job. For example, Brynjolfsson and co-authors (2023) analysed 5,000 customer support agents who were given an AI assistant trained using audio and performance metrics from agents’ interactions with customers. The AI assistant was able to increase agents’ productivity by 14% on average. Newer, less skilled, workers had a 34% improvement. Seemingly the AI assistant enabled all agents to perform as if they had the skills of the best performing agents.
To assess the economy-wide impact of AI requires a broader approach. The impact of AI will vary across different jobs, industries and sectors. It will be greatest on knowledge-based jobs and smallest on more physical jobs. Notably, this contrasts with historical technological advancements (such as mechanisation and IT) which have replaced manual jobs and simpler office jobs such as data processing.
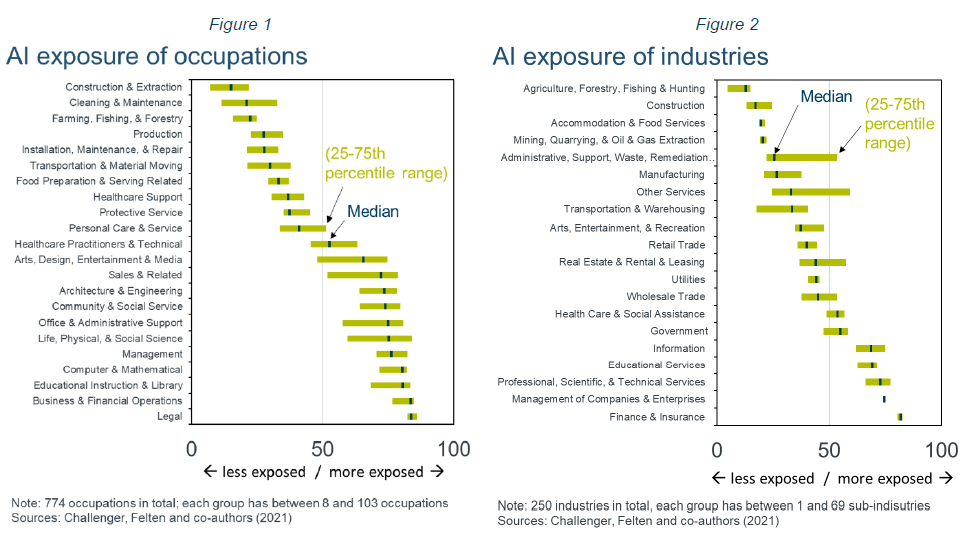
In one extensive study, Felton and co-authors (2021) considered 774 occupations across 250 industries and assessed how well 52 cognitive and physical abilities required in each of those occupations can be performed by 10 specific AI applications (such as image recognition, language modelling, and speech recognition). Aggregating such results can produce economy-wide estimates of the increase in productivity and GDP growth from AI.
There is a wide range of estimates of the impact of AI on aggregate productivity and output.
The difference in part depends on timing, whether AI is ready yet to fundamentally changes research, innovation and work practices, or whether such fundamental change requires more time.
AI will reshape the economy as some occupations (Figure 1) and industries (Figure 2) benefit more from AI than others, leading to shifts in relative prices, and importantly rising incomes and consumption.
Knowledge-based jobs are most exposed to AI. Legal jobs are most exposed, closely followed by Business & Financial Operations jobs. The industries with a larger share of knowledge jobs are most exposed to AI. Of industry groupings, Finance & Insurance is most exposed to AI.
Beyond the skills of finance workers, other factors point to the financial sector being a leader in the adoption and use of AI. The financial sector is already tech heavy and so has the capability and experience to be an early adopter. Further, many financial institutions are large and so have the scale to undertake the substantial investment to develop and utilise AI and have vast internal data needed to train AI models.
It is important to note that the sectors with the greatest exposure to AI will not necessarily have the largest increase in output. Industries that have an AI-induced productivity boom should experience a decline in their relative price and so see some increase in demand. In addition, higher productivity will increase aggregate incomes and so demand across all sectors. However, this increase in demand will be greater for sectors producing goods and services that people consume more of as they become richer, such as manufactured goods and higher quality food.
As with any significant structural change, AI brings opportunities and risks for investors. The extent of these changes will depend on the speed and breadth of the take-up and its efficacy.
AI has great promise, but there are also many risks to consider.