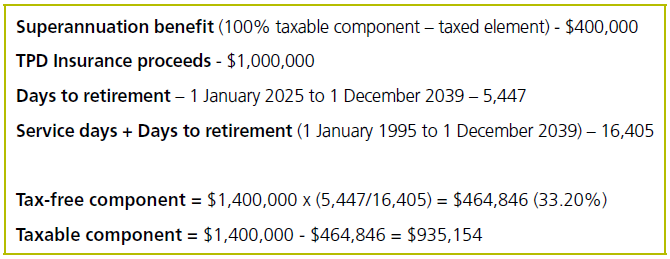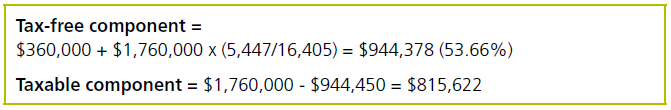Retirement savings held via superannuation are generally preserved until retirement, on or after preservation age. However, in limited circumstances the regulations make an allowance to access those savings before retirement, with one such allowance being the Permanent Incapacity (PI) condition of release. A superannuation benefit can be accessed under the PI condition of release in several ways, with each option having different tax implications which can result in very different outcomes. This article outlines the process to meet the PI condition of release and the tips, traps and pitfalls when helping your clients decide how they access their benefits.
Meeting the PI condition of release - super regulations and interaction with the tax rules
A superannuation disability benefit payable on meeting the PI condition of release can comprise of the member’s superannuation interest and insurance proceeds from a Total and Permanent Disability (TPD) policy (if any) held in that superannuation fund.
Where a TPD insurance policy is held within superannuation, the proceeds of the claim are paid to the fund. Generally, from 1 July 2014 only TPD policies that align with the PI condition of release can be held within superannuation. Individuals who are able to claim under grandfathered policies that commenced before 1 July 2014 may not subsequently access their super benefits as they may not satisfy the PI condition of release (for example own occupation TPD policies).
The SIS regulations list the eligibility conditions for meeting the PI condition of release and the Tax Act allows for the tax concessions applicable to the disability superannuation benefit.
SIS regulations1
The PI condition of release is met if the trustee is reasonably satisfied that the member is unlikely, because of physical or mental ill-health, to ever again engage in gainful employment for which the member is reasonably qualified by education, training or experience.
Income Tax Assessment Act2
A tax concession is provided if the member’s lump sum withdrawn also meets the definition of a disability superannuation benefit – a benefit paid to an individual because he or she suffers from ill-health (whether physical or mental), and two legally qualified medical practitioners have certified that, because of the ill-health, it is unlikely that the individual can ever be gainfully employed in a capacity for which he or she is reasonably qualified because of education, experience or training.
While the Tax Act definition is similar to the PI condition of release under the SIS regulations, a key difference is the requirement of two medical certificates confirming the member’s disability while the SIS regulations only require the trustee to be ‘reasonably satisfied’. In practice, trustees will usually (but not always) ask for two medical certificates to be reasonably satisfied.
Tax implications and planning considerations
Members have a number of options when accessing their benefits under the PI condition of release.
- Withdraw as a lump sum,
- Roll over to another super fund,
- Retain in accumulation phase for a future withdrawal,
- Commence an income stream, or
- A combination of these options.
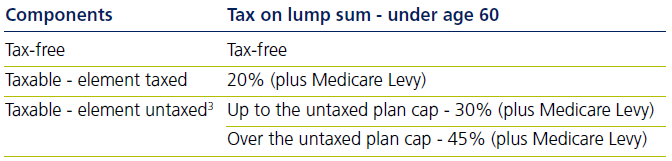
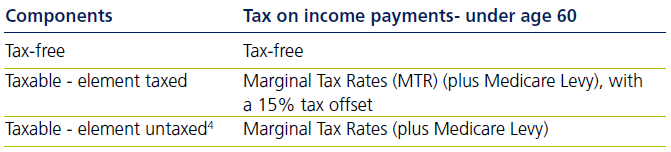
Superannuation benefits for individuals aged 60 or over are generally tax-free. However, for those under age 60, tax implications and planning considerations can differ depending on how a member chooses to access their benefit.
Withdrawing the benefit as a lump sum or rolling over to another fund
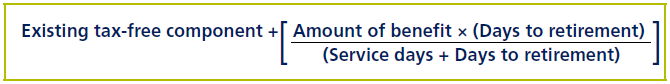
When accessing a super benefit as a superannuation disability benefit lump sum (including a rollover to another fund), a tax-free uplift can be applied by the fund that pays the lump sum or rolls over the benefit. The tax-free uplift is based on the future service period which reflects the time that the individual would have been expected to continue working had the disability not taken place.
The tax-free component of a disability lump sum is calculated using the following formula: